You’ve probably heard blockchain described as “the technology behind Bitcoin” and then heard nothing more that made sense. That’s a shame, because the core idea is simple. Once you understand it, the hype and the criticism both become much easier to judge.
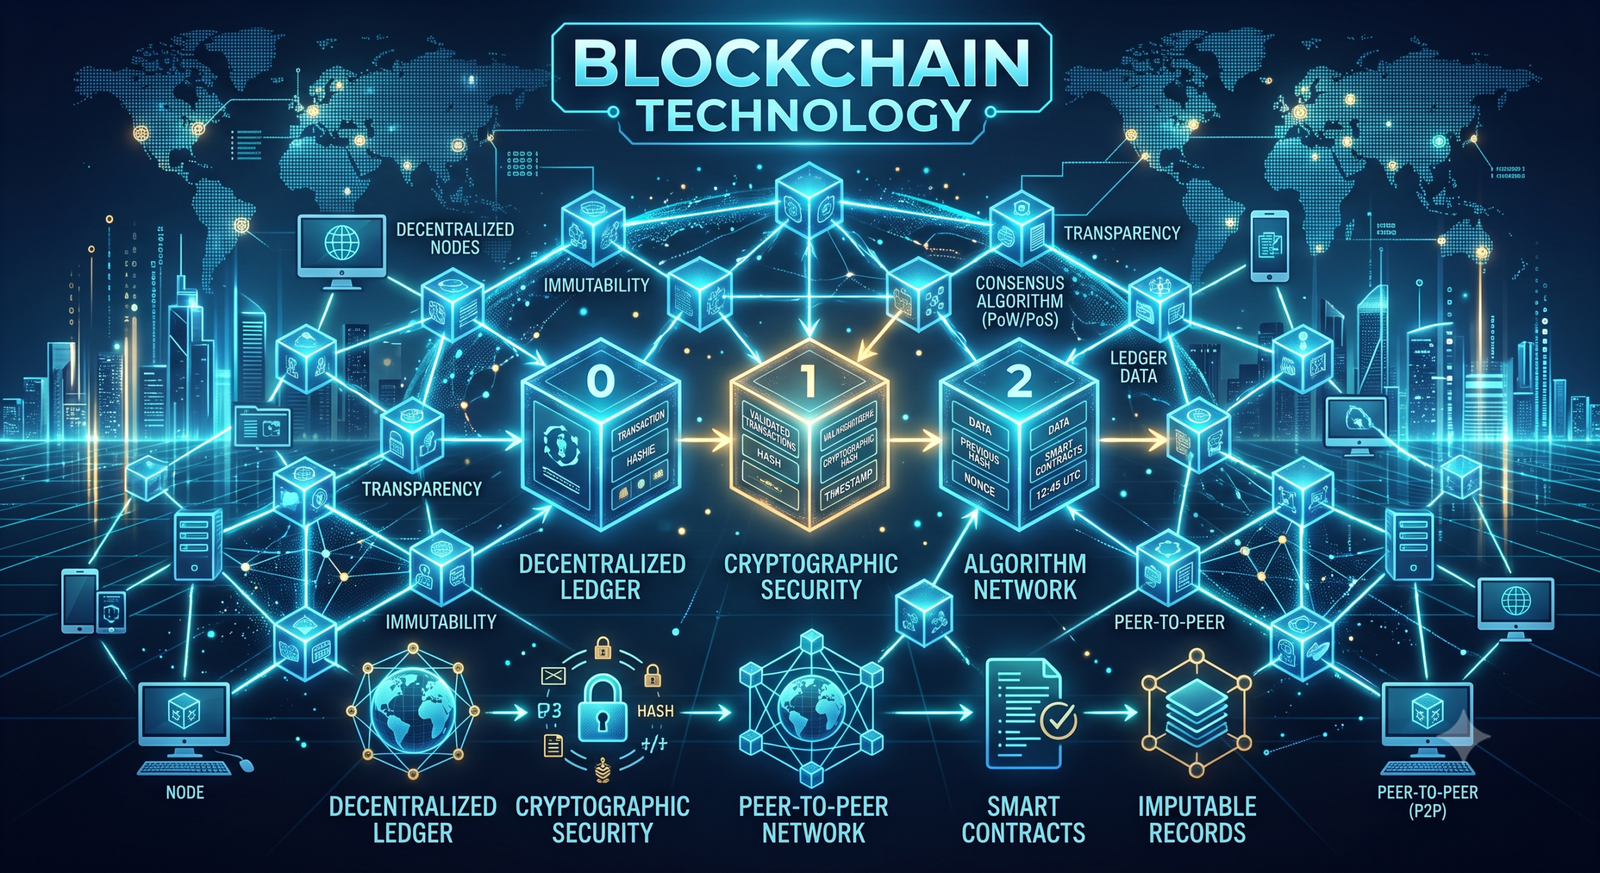
The short answer: A blockchain is a shared digital record book (a ledger) that many computers keep a copy of. New records are grouped into “blocks,” and each block is locked to the one before it using cryptography, forming a chain. Because every participant holds a copy and the blocks are linked, it’s very hard for any one person to secretly change past records.
This guide explains what blockchain technology is, how it works step by step, the different types, where it’s actually used, and where it falls short.
What Is Blockchain Technology?
At its heart, a blockchain is a database with a few unusual rules:
- It’s shared. Instead of one company holding the master copy, many computers (called nodes) each keep a full or partial copy.
- It’s append-only. You can add new records, but you can’t quietly edit or delete old ones.
- It’s ordered and linked. Records are grouped into blocks, and each block contains a fingerprint of the previous block.
- It’s agreed on by the network. Participants follow a set of rules, called a consensus mechanism, to decide which new blocks are valid.
A useful comparison is a shared Google Sheet versus a notebook in a public square.
With a normal database, one organisation controls it. If a bank says your balance is ₹10,000, you trust the bank’s records. With a blockchain, thousands of people hold identical copies of the notebook. If someone tries to rewrite a page in their copy, everyone else’s copies disagree, and the change is rejected.
That’s why blockchain is often called distributed ledger technology (DLT). The ledger is distributed across many participants, not stored in one place.
A Brief History of Blockchain
The idea of chaining records with cryptography goes back to 1991, when researchers Stuart Haber and W. Scott Stornetta proposed a way to timestamp digital documents so they couldn’t be backdated.
Blockchain became widely known in 2008, when a person or group using the name Satoshi Nakamoto published the Bitcoin white paper. Bitcoin launched in 2009 and used a blockchain to let people send digital money directly to each other without a bank.
In 2015, Ethereum launched with a bigger idea: a blockchain that could run programs, not just record payments. These programs, called smart contracts, opened the door to applications beyond currency.
Since then, businesses and governments have explored blockchain for supply chains, finance, identity, and record-keeping, with mixed results.
How Does Blockchain Work? Step by Step
Let’s follow a single transaction from start to finish. Say Priya wants to send some cryptocurrency to Rahul.
Step 1: A Transaction Is Requested
Priya creates a transaction in her digital wallet: “Send 1 coin to Rahul.” She signs it with her private key, a secret code only she holds. This digital signature proves the request really came from her, without revealing the key itself.
Step 2: The Transaction Is Broadcast to the Network
Her wallet sends the signed transaction to the network of nodes. Each node checks basic facts:
- Is the signature valid?
- Does Priya actually have the coin she’s trying to send?
- Has she already spent it somewhere else?
Valid transactions wait in a pool with other pending transactions.
Step 3: Transactions Are Grouped Into a Block
Special participants (called miners or validators, depending on the blockchain) collect pending transactions and bundle them into a new block. Each block contains:
- A list of transactions
- A timestamp
- The hash of the previous block
- Its own hash, calculated from everything inside it
Step 4: The Network Agrees the Block Is Valid
This is where the consensus mechanism comes in. The network needs a fair way to decide who gets to add the next block and whether it’s valid. The two most common methods are explained in more detail below. Once the network agrees, the block is accepted.
Step 5: The Block Is Added to the Chain
The new block is attached to the end of the chain, and every node updates its copy. Priya’s transaction is now part of the permanent record.
Step 6: The Transaction Is Complete
Rahul now owns the coin. As more blocks are added on top, the transaction becomes even harder to reverse. That’s why exchanges often wait for several “confirmations” before treating a large payment as final.
The Key Building Blocks of a Blockchain
Four concepts make the whole system work. You don’t need to understand the maths, but knowing what each piece does helps.
1. Hashing: The Digital Fingerprint
A hash function takes any data and turns it into a fixed-length string of characters. Bitcoin uses a function called SHA-256.
Hashes have two useful properties:
- The same input always gives the same output.
- Changing even one character of the input produces a completely different output.
Think of a hash as a fingerprint for data. If someone changes a single transaction in an old block, that block’s fingerprint changes completely.
2. The Chain: Why Tampering Is So Hard
Here’s the clever part. Every block stores the hash of the block before it.
So if someone edits Block 100, its hash changes. Block 101 still points to the old hash, so the link breaks. To hide the edit, the attacker would have to recalculate Block 101, then 102, then 103, and every block after that. They’d also have to do it faster than the rest of the network keeps adding new blocks, and convince most of the network to accept their version.
On a large, well-established blockchain, that’s impractical. This is what people mean when they call blockchain immutable. It isn’t strictly impossible to change, but it’s extremely difficult and expensive.
3. Public and Private Keys: Proving Ownership
Every user has a pair of cryptographic keys:
- A public key (or an address derived from it), which works like an account number. You can share it freely.
- A private key, which works like a password and a signature combined. You never share it.
Whoever holds the private key controls the assets linked to that address. That’s why losing a private key usually means losing access to those funds permanently. There’s no “forgot password” button.
4. Consensus Mechanisms: How Strangers Agree
In a network of computers that don’t trust each other, how do you agree on which records are true? Consensus mechanisms solve this problem.
Proof of Work (PoW)
Miners compete to solve a difficult mathematical puzzle. The first to solve it gets to add the next block and earns a reward. Solving the puzzle takes a lot of computing power, which makes attacks costly.
Bitcoin uses Proof of Work. It’s proven to be very secure, but it uses a large amount of electricity.
Proof of Stake (PoS)
Instead of burning computing power, validators lock up (or “stake”) some of their own cryptocurrency as collateral. The network picks validators to propose and confirm blocks. If a validator cheats, it can lose part of its stake.
Ethereum switched from Proof of Work to Proof of Stake in 2022, in an upgrade known as “The Merge.” This cut its energy use dramatically.
There are other methods too, such as Delegated Proof of Stake and Proof of Authority. Most of these are variations that trade some decentralisation for speed.
Types of Blockchain
Not every blockchain is open to everyone. There are four main types.
| Type | Who Can Join | Who Controls It | Common Uses |
|---|---|---|---|
| Public | Anyone | No single owner | Cryptocurrencies, open applications |
| Private | Invited participants only | One organisation | Internal records, auditing |
| Consortium | Selected organisations | A group of organisations | Banking networks, trade finance |
| Hybrid | Mix of public and private access | Varies | Supply chains, regulated industries |
Public blockchains like Bitcoin and Ethereum are fully open. Anyone can read the ledger, send transactions, or run a node. They offer the most decentralisation but can be slower and more expensive to use.
Private blockchains are run by a single organisation that decides who can participate. They’re faster and more private but give up much of the decentralisation that makes blockchain unique.
Consortium blockchains are shared among a group, such as several banks or shipping companies. No single member controls the network, but outsiders can’t join freely.
Hybrid blockchains keep some data private while making certain records public or verifiable.
What Are Smart Contracts?
A smart contract is a small program stored on a blockchain that runs automatically when certain conditions are met.
A simple example is a crop insurance policy. The smart contract could say: “If official rainfall data shows less than a set amount in this district during the monsoon, pay the farmer automatically.” No claim form, and no waiting for an adjuster.
Smart contracts power much of what’s built on blockchains today, including decentralised finance (DeFi) apps, NFTs, and token systems.
The catch is that code does exactly what it’s written to do, including bugs. Flawed smart contracts have led to significant losses, so auditing and careful design matter a lot.
Real-World Uses of Blockchain Technology
Blockchain is most useful when several parties who don’t fully trust each other need to share a reliable record. Here are some areas where it’s been applied.
Cryptocurrency and Payments
This is the original use case. Bitcoin, Ethereum, and other cryptocurrencies let people transfer value across borders without a traditional intermediary. Stablecoins, tokens designed to track a currency like the US dollar, are widely used for payments and settlements on blockchain networks.
Supply Chain Tracking
Companies have used blockchain to track goods from source to shelf. For example, a food retailer can record each step of a product’s journey, from farm to warehouse to store. If a contamination problem appears, tracing the source takes far less time.
Banking and Trade Finance
Cross-border payments and trade finance involve a lot of paperwork and many intermediaries. Consortium blockchains aim to let banks share verified documents and settle transactions faster.
Digital Identity and Credentials
Universities and certification bodies can issue credentials that anyone can verify on a blockchain. That makes fake degrees and certificates easier to spot.
Healthcare Records
Blockchain can create an auditable log of who accessed a patient’s records and when. The medical data itself usually stays off-chain for privacy reasons.
Land and Property Records
Several governments, including some Indian states, have tested blockchain for land records. The goal is to reduce disputes and fraud by creating a tamper-evident history of ownership.
Tokenisation of Assets
Real-world assets such as bonds, funds, and real estate can be represented as digital tokens on a blockchain. This can make trading, settlement, and fractional ownership simpler, though it’s still an evolving and heavily regulated area.
Benefits of Blockchain Technology
When used in the right situation, blockchain offers real advantages:
- Tamper resistance: Past records are very hard to change without detection.
- Transparency: On public blockchains, anyone can verify transactions.
- No single point of failure: Because many nodes hold copies, the network keeps running even if some go offline.
- Fewer intermediaries: Parties can transact directly, which can reduce cost and delay.
- Automation: Smart contracts can carry out agreements without manual steps.
- Clear audit trail: Every change is recorded with a timestamp.
Limitations and Challenges
Blockchain isn’t a magic fix, and it’s worth being honest about its weaknesses.
Speed and scalability. Public blockchains process far fewer transactions per second than traditional payment networks. Solutions like “layer 2” networks, which handle transactions off the main chain and settle them later, help but add complexity.
Energy use. Proof of Work blockchains consume large amounts of electricity. Proof of Stake systems use far less.
Irreversibility. If you send funds to the wrong address or lose your private key, there’s usually no way to undo it.
“Garbage in, garbage out.” A blockchain can prove a record hasn’t been changed, but it can’t prove the record was true to begin with. If someone enters false data, the blockchain will faithfully preserve that false data.
Regulation and legal uncertainty. Rules on cryptocurrency and digital assets vary by country and continue to change. In India, for example, crypto gains are taxed, but the wider regulatory framework is still developing.
Often unnecessary. Many projects that claim to need blockchain would work just as well, or better, with a regular database. If a single trusted organisation controls the data, a blockchain usually adds cost without much benefit.
Blockchain vs Traditional Database
| Feature | Blockchain | Traditional Database |
|---|---|---|
| Control | Shared across many participants | One organisation |
| Editing records | Append-only, very hard to change | Records can be edited or deleted |
| Trust model | Trust in the rules and cryptography | Trust in the organisation |
| Speed | Generally slower | Generally faster |
| Transparency | Often high (for public chains) | Usually private |
| Best for | Multiple parties who don’t fully trust each other | A single organisation managing its own data |
A simple rule of thumb is this. If several independent parties need to share and trust the same data, and no one party should control it, blockchain may be a good fit. If not, a traditional database is usually the better choice.
Frequently Asked Questions
Is blockchain the same as Bitcoin?
A. No. Bitcoin is a cryptocurrency that runs on a blockchain. Blockchain is the underlying technology, and it’s used for many things besides Bitcoin.
Can a blockchain be hacked?
A. The core structure of a large, well-established blockchain is very hard to attack. But the things built around it, such as exchanges, wallets, and smart contracts, can have weaknesses. Most losses come from these, or from users having their private keys stolen.
Who controls a blockchain?
A. Public blockchains have no single owner. They’re maintained by their community of nodes, validators, and developers. Private and consortium blockchains are controlled by one organisation or a group.
What is a node in blockchain?
A. A node is a computer that connects to the blockchain network, keeps a copy of the ledger, and helps check and relay transactions and blocks.
Is blockchain technology secure?
A. Its design makes past records highly resistant to tampering. But overall security also depends on how applications are built and how users protect their keys.
Do I need to buy cryptocurrency to use blockchain?
A. Not always. Many business blockchains don’t involve public cryptocurrencies at all. On public blockchains, though, you usually need a small amount of the network’s native token to pay transaction fees.
The Bottom Line
Blockchain technology is a shared, tamper-resistant record book kept by many computers at once. Transactions are grouped into blocks, each block is locked to the previous one with a cryptographic fingerprint, and the network agrees on new blocks through a consensus mechanism. That combination lets people who don’t know or trust each other rely on the same set of records.
It’s powerful in the right setting, especially where several parties need a shared, verifiable history. It’s not the right tool for every problem. The most useful question to ask about any blockchain project is simple: what does this do that a regular database couldn’t?